

Insurance is the boring part of opening a venue until something goes wrong. A guest trips on a step. A tent blows over. A groomsman puts a chair through a wall. Then it’s the most important paper you own. This isn’t insurance advice, and prices and rules change by state and by company. It’s a plain list of what to ask about before you book your first couple in the USA. If you want the full picture too, this wedding venue business guide covers every step from first idea to first booking.
Talk to a broker first
Don’t just buy the first policy you see online. Talk to two or three brokers who work with event venues. Tell them everything. How many guests, indoor or outdoor, if you serve alcohol, if you have staff, how many events a year. Then ask them to explain each cover in simple words. If they use big words, ask again. A good broker doesn’t mind.
Property insurance
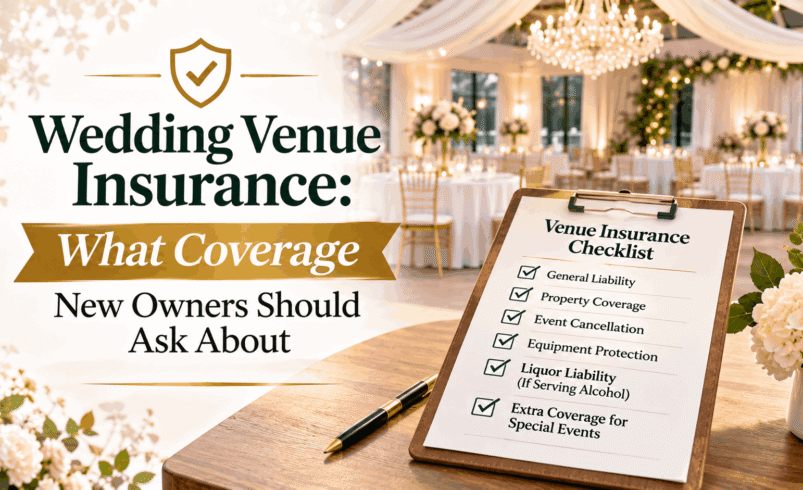
This covers your building and the stuff inside it, if something bad happens like a fire or storm damage. Ask what’s covered and what’s not. Ask if it still applies when you host paid events, because some regular policies don’t. Make a list of what you own too, like tables, chairs, lights, a bar and commercial buffet counters. Ask if these are counted as part of the policy, and how much it would cost to replace them. Built to fit pieces can cost more to replace than people expect.
General liability
This is the big one for venues. It helps pay if a guest or vendor gets hurt on your property, or if someone says you caused damage. Ask how much coverage you need, and what it does and doesn’t cover. Some policies have limits for things like events, outdoor spaces or certain activities. Don’t assume. Ask.
Liquor liability
If alcohol is served, ask about this one for sure. It’s different from general liability, and a lot of policies don’t include it. Rules about alcohol change a lot by state, and some states can hold a venue responsible if a guest gets hurt after drinking. Ask your broker how it works where you are. Also ask if it matters who pours the drinks, you, a licensed bar company or a caterer.
Workers’ comp
If you have staff, like a coordinator, bartenders or a cleanup crew, many states require workers’ comp. It helps pay if an employee gets hurt on the job. Rules differ on who counts as an employee and who counts as a contractor. Ask your broker and your state office so you don’t get it wrong.
Vendor insurance papers
Photographers, DJs, caterers, bartenders and florists all work on your property. Ask each one for a certificate of insurance before the event. It’s a simple paper that shows they have coverage. Many venues also ask to be named on the vendor’s policy, which is called an additional insured. Ask your broker how to word this. Keep every certificate in one folder with the dates, because policies run out.
One day event policies
Many venues ask couples to buy a one day event policy. It can cover things like guest injuries or damage during the wedding. Ask your broker if you should require this, and write it into your contract. Tell couples early, so it isn’t a surprise a week before the wedding.
Cancellations and weather
Weddings get cancelled. Storms hit, vendors back out and couples break up. Ask your broker what your own policy covers, if anything, when an event is cancelled. Couples can also buy their own cancellation cover, so ask if you should suggest it. Then make your contract clear about deposits and refunds, since a vague contract causes more fights than any storm.
Damage claims and deposits
Plan how you’ll handle damage before it happens. Many venues take a refundable damage deposit. Put the amount, what counts as damage and how fast you’ll return it in writing. Take photos of the space before and after each event. If a claim comes up, those pictures and your contract will matter a lot. Ask your broker how to file a claim and how long it takes, so you aren’t learning on the worst day.
Outdoor and special items
Tents, bounce houses, fireworks, live animals and food trucks can all change your insurance. Some need extra cover, and some may not be allowed at all. Ask before you say yes to a couple. A lot of problems start with “sure, why not.”
Ask about the gaps
At the end, ask your broker one simple question. What is NOT covered? The answer is often the most useful part. Maybe your policy leaves out certain damage, or caps what it pays for some claims. Better to hear it now than after a claim is denied.
Keep everything in writing
Save your policies, certificates, contracts and photos in one place, paper or online. Put renewal dates on your calendar. A policy that runs out by accident can leave you with zero cover on a busy weekend.
Final thoughts
Insurance isn’t exciting, but it protects your business, your staff and your couples. Ask about property, general liability, liquor liability and workers’ comp. Collect papers from every vendor, plan your deposits and ask what isn’t covered. Talk to a few brokers, get answers in writing and keep it all organized. Do that before your first booking, and you’ll walk into every event with a lot less worry.