

Staffing agencies occupy a unique position in the employment landscape. You hire workers, train them, and place them at client sites—yet you maintain responsibility for their wellbeing even when they’re not under your direct supervision. This creates a complex risk environment where workers comp for staffing agencies becomes not just a legal requirement, but a critical business strategy.
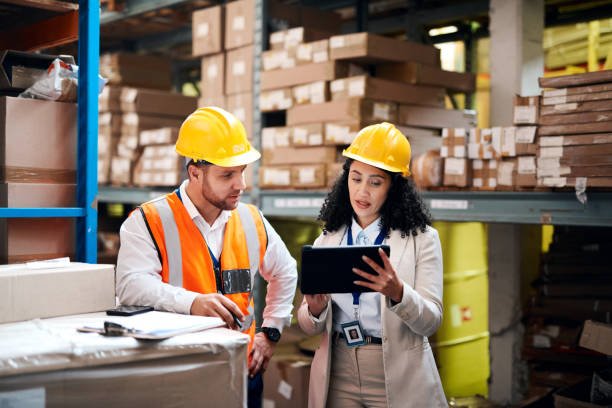
Unlike traditional employers who control their work environments, staffing firms deploy employees across multiple locations with varying safety conditions. A clerical worker placed at a quiet office faces vastly different risks than a warehouse associate operating heavy machinery. This diversity of exposures makes workers compensation for staffing agencies more complicated—and more important—than coverage for most other industries.
This guide explores everything staffing agency owners and insurance professionals need to know about workers compensation for staffing agencies, from coverage fundamentals to cost management strategies.
What Is Workers Comp for Staffing Agencies?
Workers compensation insurance provides medical benefits and wage replacement for employees injured on the job. For staffing agencies, this coverage extends to all temporary and contract workers placed at client sites.
The staffing agency serves as the employer of record, meaning your firm retains legal responsibility for providing workers compensation coverage regardless of where employees work or who supervises them daily. This principle holds even when temporary workers perform tasks under client direction.
Standard workers comp coverage for staffing agencies typically includes medical care for work-related injuries, disability benefits replacing lost wages, rehabilitation costs, and death benefits for fatal workplace incidents. The coverage also protects your staffing business from lawsuits arising from workplace injuries.
Why Staffing Agencies Need Workers Comp Insurance
The legal landscape makes workers compensation insurance mandatory for most staffing agencies. Every state except Texas requires employers to carry coverage, and staffing firms face particular scrutiny because they employ workers in inherently varied and sometimes dangerous environments.
Beyond legal compliance, workers comp for staffing agencies provides essential financial protection. A single severe injury—a warehouse worker with a spinal cord injury, for example—can generate medical costs exceeding hundreds of thousands of dollars. Without proper coverage, these expenses could devastate your business.
Your clients also depend on your workers comp coverage. Many client contracts require staffing agencies to maintain adequate insurance, and proof of coverage often determines whether you win or lose placement opportunities. Reputable clients want assurance that any worker injury won’t become their liability.
The Classification Challenge
Perhaps the most significant complexity in workers comp for staffing agencies involves job classification accuracy. Premiums are calculated based on the type of work employees perform, and each classification carries a different risk rating.
A clerical worker classified as light industrial might pay significantly higher premiums than necessary. Conversely, misclassifying a warehouse worker as clerical could lead to denied claims and audit penalties when injuries occur.
The challenge intensifies with task creep—the gradual drift of job duties beyond original classifications. A worker hired for light packaging might begin operating machinery during busy periods. A front-desk employee could start lifting heavy supplies. When injuries occur during these out-of-classification tasks, insurers may dispute coverage.
Staffing agencies must implement systems to monitor actual job duties, maintain clear communication with clients about role changes, and document everything thoroughly.
Cost Factors and Premium Calculation
Several variables influence workers compensation costs for staffing agencies:
Industry risk plays the largest role. Placing workers in construction, manufacturing, or healthcare generates higher premiums than clerical or professional placements.
Payroll size directly affects premiums since workers comp is typically calculated per $100 of payroll. Staffing agencies with high turnover and fluctuating headcounts may see significant premium variations.
Claims history and your experience modification rate (EMR) determine whether you pay more or less than industry averages. A strong safety record can reduce premiums substantially over time.
State regulations create geographic variations in rates, coverage requirements, and reporting obligations.
Strategies to Reduce Workers Comp Costs
Effective risk management can significantly reduce workers comp expenses for staffing agencies.
Invest in safety training for temporary workers. Since temps often receive less comprehensive orientation than permanent employees, brief but focused safety training can reduce injury frequency.
Conduct client site assessments before placing workers. Understanding workplace hazards helps you match workers appropriately and identify unsafe conditions.
Implement return-to-work programs. Getting injured employees back to productive work quickly reduces claim costs and supports better outcomes.
Choose specialized coverage. Staffing-focused insurers understand your industry’s unique exposures and may offer more competitive rates than general carriers.
Monitor classifications continuously. Regular reviews ensure your premiums reflect actual work being performed, preventing both overpayment and audit surprises.
Conclusion
Workers compensation for staffing agencies represents both a fundamental compliance obligation and a strategic opportunity. By understanding classification requirements, implementing robust safety programs, and partnering with specialized insurers, staffing firms can control costs while protecting their most valuable asset—their workforce.
The complexity of this coverage demands attention. Job duties evolve, workers move between assignments, and regulations vary by state. Staffing agencies that proactively manage these variables position themselves for sustainable success and stronger client relationships.
10 FAQs About Workers Comp for Staffing Agencies
1. Are staffing agencies legally required to carry workers comp?
Yes, in nearly all states. Staffing agencies serve as the employer of record and must provide workers compensation coverage for all placed employees.
2. Who pays for workers comp—the staffing agency or the client?
The staffing agency typically pays premiums as the employer of record. Some agencies may negotiate cost-sharing arrangements with clients, but the legal obligation remains with the staffing firm.
3. What happens if a worker is injured performing tasks outside their classification?
This is called “task creep” and can lead to claim disputes, audit penalties, and premium adjustments. Insurers evaluate actual work performed, not just job descriptions.
4. How much does workers comp cost for staffing agencies?
Costs vary dramatically based on industry, state, payroll, and claims history. The Hartford reports average workers comp costs around $86 monthly for staffing agencies, though high-risk placements cost considerably more.
5. Can staffing agencies use pay-as-you-go workers comp?
Yes, many specialized carriers offer pay-as-you-go options that align premiums with actual payroll, which benefits agencies with fluctuating staffing levels.
6. What is an experience modification rate (EMR)?
Your EMR is a safety score comparing your claims history to industry averages. Lower EMRs mean lower premiums; higher EMRs indicate more claims and higher costs.