

A business can generate strong sales and still struggle to pay its bills on time. This often happens when money takes too long to arrive from customers while supplier payments, salaries, rent and other expenses are due.
Managing this gap between incoming and outgoing money is one of the biggest financial challenges for growing businesses. Without proper planning, companies may face cash shortages, delay supplier payments or struggle to cover everyday operating costs.
Effective cash flow management for businesses helps owners understand when money will come in, when payments are due and how much cash will remain available. It also helps companies balance customer collections with supplier obligations and make better financial decisions.
The goal is not simply to increase sales or reduce expenses. Businesses need a reliable system for managing both sides of their cash flow.
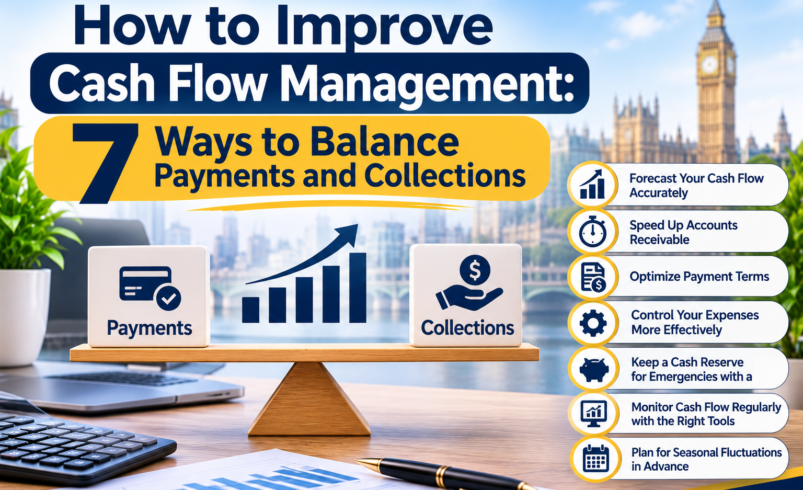
Here are seven practical ways to balance payments and collections, improve cash availability and support sustainable business growth.
1. Prepare a Regular Cash Flow Forecast
A cash flow forecast helps businesses estimate how much money they expect to receive and pay over a specific period.
It gives business owners a clearer picture of future cash requirements and helps them identify potential shortages before they become serious problems.
Start by listing all expected cash inflows, including:
- Payments from customers.
- Sales revenue.
- Advance payments.
- Investment received.
- Loan proceeds.
- Other business income.
Next, record expected cash outflows, such as:
- Supplier payments.
- Employee salaries.
- Office rent and utilities.
- Marketing expenses.
- Loan repayments.
- Tax payments.
- Equipment purchases.
- Other operating costs.
The important point is to record when money is expected to enter or leave the business, not simply when a sale or expense is recorded.
For example, a company may issue an invoice worth AED 50,000 in November but expect to receive payment in December. The forecast should show the expected cash receipt in December.
Prepare forecasts monthly or weekly, depending on the size and transaction volume of your business.
A rolling cash flow forecast is also useful. It allows you to update future estimates regularly using actual payments and the latest financial information.
This helps management understand upcoming financial commitments and plan spending more carefully.
2. Improve Accounts Receivable and Collect Customer Payments Faster
Outstanding customer invoices are one of the common reasons businesses experience cash flow pressure.
When customers delay payments, businesses may struggle to meet their own financial obligations even when they have completed the work and recorded the revenue.
Improving accounts receivable management can help reduce these delays and bring cash into the business more quickly.
Start by establishing clear payment terms before providing products or services. Customers should know the payment deadline, accepted payment methods and any agreed late payment conditions.
You can also improve collections by:
- Sending invoices immediately after completing work.
- Checking invoice details before sending them.
- Setting clear payment deadlines.
- Sending reminders before invoices become overdue.
- Following up on outstanding balances.
- Offering convenient payment options.
- Reviewing customer payment histories.
For example, if your business gives customers 30-day payment terms, send a reminder before the deadline and follow up promptly if payment is not received.
An accounts receivable aging report can help identify which customers have overdue balances and how long invoices have remained unpaid.
Prioritise high-value overdue invoices and customers with repeated payment delays.
A consistent collection process can reduce outstanding balances and make incoming cash more predictable.
3. Manage Accounts Payable and Schedule Supplier Payments
Collecting money from customers is only one part of cash flow management. Businesses must also control when money leaves their accounts.
Accounts payable management helps companies organise supplier invoices, monitor payment deadlines and avoid unnecessary pressure on available cash.
Start by maintaining a complete record of supplier obligations. Each invoice should include the supplier name, amount, due date and agreed payment terms.
Then create a payment schedule to organise upcoming payments.
Consider the following practices:
- Review supplier invoices before approving payments.
- Track all payment deadlines.
- Avoid duplicate or unauthorised payments.
- Use agreed payment terms effectively.
- Negotiate longer payment periods where possible.
- Take early payment discounts when financially beneficial.
- Prioritise essential suppliers and obligations.
For example, a company may have several supplier invoices due during the same week. Reviewing these obligations in advance helps management decide how to allocate available cash.
However, delaying payments without agreement can damage supplier relationships and lead to penalties. The aim is to schedule payments responsibly while protecting the company’s cash position.
Businesses should also compare supplier payment dates with expected customer collections. This makes it easier to identify periods when outgoing payments may exceed incoming cash.
4. Control Operating Expenses Without Affecting Essential Activities
High operating expenses can reduce the amount of cash available for daily business activities.
As companies grow, they often add employees, purchase additional supplies, subscribe to new software and increase marketing spending. These costs can rise quickly if they are not monitored.
Review your regular expenses and identify areas where spending can be improved.
Common expense categories to examine include:
- Office rent and utilities.
- Employee and administrative costs.
- Software subscriptions.
- Marketing and advertising.
- Transportation and delivery.
- Equipment maintenance.
- Professional service fees.
- Inventory and supplies.
Separate essential costs from expenses that can be reduced or postponed.
For example, a business may discover that it is paying for several software subscriptions with similar features. Removing unused services can reduce monthly expenses without affecting operations.
It is also useful to compare supplier prices and review existing contracts. Negotiating better terms may help reduce purchasing costs.
However, avoid cutting expenses that directly support revenue, customer satisfaction or operational quality.
Reducing effective marketing activities or removing essential staff may save money temporarily but could weaken future business performance.
A well-managed expense budget helps businesses protect available cash while continuing to invest in growth.
5. Maintain Sufficient Working Capital
Working capital represents the short-term financial resources available to support everyday business operations.
It is generally calculated as:
Working Capital = Current Assets – Current Liabilities
Current assets may include cash, accounts receivable and inventory, while current liabilities may include supplier balances and other short-term obligations.
Maintaining sufficient working capital helps businesses pay employees, purchase supplies and meet regular financial commitments.
However, having positive working capital does not always mean that cash is readily available. A large amount tied up in unpaid invoices or unsold inventory may still create payment difficulties.
To manage working capital effectively:
Reduce outstanding customer balances
Follow up on overdue invoices and improve collection procedures.
Monitor inventory levels
Avoid purchasing more stock than the business can reasonably sell.
Review supplier payment terms
Organise payments around agreed deadlines and expected cash receipts.
Maintain a cash reserve
Keep enough accessible funds to manage unexpected expenses and temporary cash shortages.
For example, a trading company may hold a large amount of money in inventory. If products take several months to sell, the business may struggle to pay suppliers and employees.
Reviewing inventory turnover and purchasing requirements can help release cash for other activities.
Working capital planning is especially important when businesses expand, increase production or enter new markets.
6. Use Financial Reports and Cash Flow Metrics to Monitor Performance
Businesses need accurate financial information to understand whether their cash flow management strategies are working.
Regular financial reports help management identify payment delays, rising expenses and changes in available cash.
Some useful reports include:
- Cash flow statement: Shows cash received and paid during a reporting period.
- Accounts receivable aging report: Identifies outstanding customer invoices by age.
- Accounts payable aging report: Shows unpaid supplier invoices and their due dates.
- Profit and loss statement: Summarises revenue, expenses and profitability.
- Balance sheet: Shows assets, liabilities and equity at a particular date.
In addition to reports, businesses should monitor important cash flow indicators.
| Metric | What It Helps Measure |
|---|---|
| Operating cash flow | Cash generated through normal business activities |
| Days Sales Outstanding (DSO) | Average time taken to collect customer payments |
| Days Payable Outstanding (DPO) | Average time taken to pay suppliers |
| Current ratio | Ability to meet short-term liabilities using current assets |
| Cash conversion cycle | Time taken to convert business investment in inventory and operations into cash |
These metrics provide useful information about the company’s financial position.
For example, an increase in DSO may indicate that customers are taking longer to pay. Management can investigate the cause and improve collection procedures.
Similarly, a high level of overdue supplier invoices may indicate that the business needs to review its cash flow forecast or payment schedule.
Review these reports regularly rather than waiting until the end of the financial year.
7. Use Accounting Software and Automation to Improve Cash Flow Control
Managing payments, invoices and financial records manually can become difficult as a business grows.
Finance teams may need to track hundreds of customer invoices, process supplier payments and update accounting records. Manual work can increase errors and make it harder to identify cash flow problems quickly.
Accounting software can help organise these activities and provide better financial visibility.
Depending on the system, businesses may be able to:
- Generate and send customer invoices.
- Schedule payment reminders.
- Record incoming payments.
- Track outstanding customer balances.
- Process supplier invoices.
- Monitor upcoming payment deadlines.
- Reconcile bank transactions.
- Prepare cash flow reports.
- Review accounts payable and receivable balances.
Some systems also support automated reporting and integration with banking platforms.
For example, a business can use accounting software to monitor overdue customer invoices while keeping a separate record of supplier payments due during the same period.
This helps finance teams compare incoming and outgoing cash more efficiently.
Automation can reduce repetitive administrative work, but it should not replace financial reviews and approval controls. Employees should still check important transactions, investigate unusual activity and verify financial reports.
Choose a system that matches your business size, transaction volume and reporting requirements.
Common Cash Flow Management Mistakes Businesses Should Avoid
Even businesses with regular sales and established accounting processes can make mistakes that affect cash availability.
Some common issues include:
1. Confusing profit with cash flow
A profitable business may still face cash shortages when customers delay payments or expenses become due before cash is received.
2. Sending invoices late
Delaying invoices also delays the start of the customer’s payment period.
3. Ignoring overdue receivables
Unpaid invoices can build up and increase the risk of bad debts.
4. Paying suppliers without planning
Making payments without reviewing upcoming obligations can leave insufficient cash for essential expenses.
5. Holding excessive inventory
Unsold stock ties up money that could be used for other business activities.
6. Failing to update cash flow forecasts
Outdated forecasts may not reflect changes in sales, costs or payment schedules.
7. Relying on manual financial tracking
Poorly organised records make it harder to identify problems and prepare accurate reports.
Avoiding these mistakes can help businesses maintain better control over their finances and respond to cash flow challenges earlier.
How Professional Accounts Payable and Receivable Services Support Cash Flow Management
Managing cash flow requires coordination between customer collections and supplier payments. Businesses need accurate records, reliable reporting and consistent financial procedures to keep both activities organised.
Professional accounts payable and receivable support can help businesses improve these processes.
For example, accounts receivable support can help monitor outstanding customer balances, prepare aging reports and follow up on overdue invoices. Accounts payable support can help organise supplier invoices, track payment deadlines and reconcile supplier statements.
These activities contribute to better financial visibility and more informed cash management.
Dubai Business and Tax Advisors (DBTA) provides accounts payable and receivable services to help businesses manage incoming and outgoing payments, maintain accurate records and improve financial processes. Its budgeting and forecasting services can also support businesses in estimating future cash requirements and planning their expenditure.
For businesses operating in Dubai and across the UAE, organised financial records also help support bookkeeping, financial reporting and applicable tax responsibilities.
Conclusion
Effective cash flow management is essential for maintaining business stability and supporting long-term growth. A company needs to collect customer payments on time while ensuring that supplier invoices and operating expenses are paid responsibly.
The seven strategies discussed in this guide provide a practical approach to improving cash flow management for businesses. Preparing cash flow forecasts, improving customer collections, scheduling supplier payments and controlling expenses can help businesses maintain better financial balance.
Regularly reviewing working capital, financial reports and payment performance is equally important. Accounting software can also make these processes more efficient as transaction volumes increase.
Remember that strong cash flow management is not just about having more money coming in. It is about managing the timing of payments and collections so that the business has enough cash to meet its obligations and invest in future opportunities.